

Most ESG procurement report examples you can find online are built around a single-material swap case study, something like replacing plastic drums with paper cans, or switching office supplies to eco-friendly alternatives.
The whole report’s logic boils down to “we swapped this one material, and here’s how much carbon we saved.”
Food container procurement usually isn’t that simple. Most companies are buying kraft paper, plant fiber, and plastic at the same time, each with different sustainability claims, test standards, and certification systems.
Forcing a single-material swap narrative onto that mix tends to fall apart under review, the moment someone asks “what about the plastic containers,” the whole report’s argument stops holding up.
This guide is about report structure and how to fill it out, not the carbon footprint calculation itself. The calculation involves enough detail around conversion factors and scope boundaries that it deserves its own piece, which we’ll cover separately.
Why a Single-Material Swap Case Study Doesn’t Work as a Template
A single-material swap case has simple narrative logic: there’s a clear before and after, and the difference between them is the result.
A multi-material procurement mix doesn’t have a single “before” baseline. Kraft paper containers might already be in use, plant fiber containers were introduced last year, and plastic containers are deliberately kept on certain product lines as a durability and cost tradeoff, the same logic covered in our earlier piece, Mixing Plastic and Plant Fiber Container Sourcing: Lower Cost While Meeting ESG Goals.
Forcing a single-material narrative onto that reduces a multi-variable procurement decision into a false “complete green transition” story, and the moment someone asks for the corresponding data on the plastic side, the report turns out never to have covered it.
The 4 Sections a Real ESG Procurement Report Needs
Section 1: Procurement Policy and Green Metric Definitions
This section needs to spell out exactly what your company means by “sustainable procurement,” with specific green metrics listed, not a line like “committed to purchasing more eco-friendly packaging” and nothing else.
Common green metrics worth including: compostability certification coverage (ASTM D6400, EN 13432), the share of material sourced under FSC or PEFC certification, PFAS-free declaration coverage, and where your per-unit carbon emission factor comes from, supplier-provided data or a third-party industry average.
None of these metrics need to hit a target before they belong in the report. What matters is reporting the actual current number honestly for each one, even “not yet tracked” holds up better under review than leaving it out entirely.
Section 2: Supplier ESG Qualifications and Certification Proof
This section tends to get written as one vague line, “all suppliers meet international certification standards,” but the first thing a reviewer asks is which certification, which supplier, and when it expires.
If your kraft paper, plant fiber, and plastic containers come from different suppliers, this section needs to list each supplier separately, with certificate numbers, expiration dates, and third-party test report numbers attached, not folded into one vague summary paragraph.
For a general framework on evaluating supplier qualifications, see How Do You Evaluate a Food Container Supplier? 8 Questions That Apply Across Materials. The checklist items there convert directly into the supporting evidence this section needs.
Section 3: Quantifying the Procurement Mix
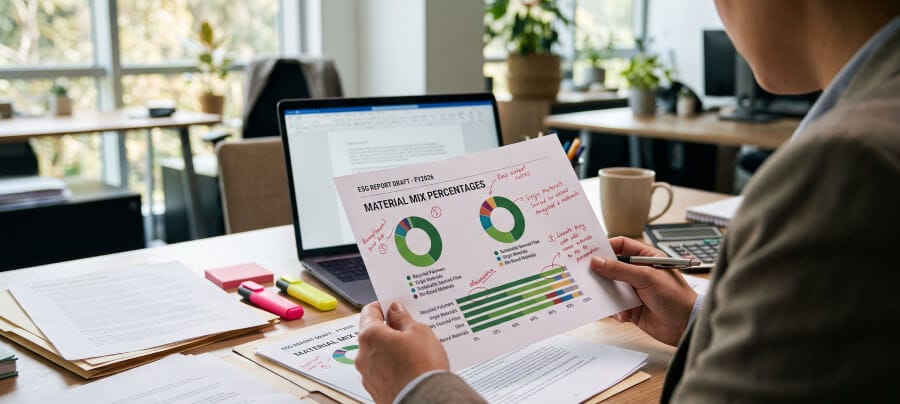
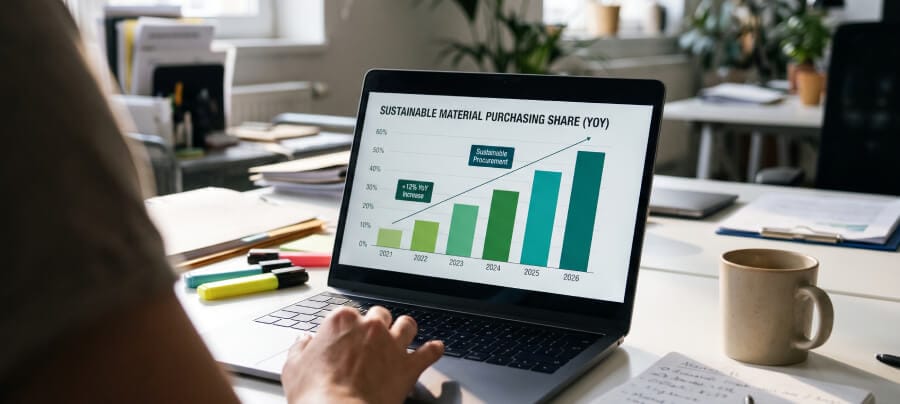
This section isn’t about a carbon footprint formula. It’s about showing a year-over-year comparison of material mix, for example, “sustainable material (plant fiber plus FSC-certified kraft paper) share of purchasing rose from 15% last year to 32% this year.”
That kind of comparison carries more weight than simply stating how much sustainable material you used, because it shows a trend, not a single point in time.
Going a step further, this section is also worth using to explain why the number is 32% and not 100%, rather than letting the reader assume anything short of a full switch means not trying hard enough.
You can draw directly on the cost math logic here, which product lines got prioritized because of consumer visibility, which stayed on plastic for durability and cost reasons, so the report reads as a financially grounded decision rather than just a set of green numbers.
Section 4: Next Year’s Targets and Tracking Mechanism
Targets need a specific number and a date, for example, “raise sustainable material share to 45% by the end of next year,” rather than an open-ended goal like “continue increasing sustainable procurement,” which makes it impossible to judge next year whether you actually hit it.
The tracking mechanism should name who’s responsible for updating the data and how often it gets reviewed. A common approach is tying it to an existing procurement meeting cadence, reviewing material mix and supplier certification expiration dates at each quarterly procurement meeting, rather than scrambling to compile everything right before the annual report deadline.
The 3 Most Common Mistakes
The first mistake is treating a single-material swap as a stand-in for the whole company’s results, only to discover during an audit that the other materials were never covered, and scrambling to pull together data at the last minute.
The second mistake is writing the conclusion without the method, something like “cut emissions by 20%” with no explanation of the calculation scope or conversion factors used. When an external ESG rating body or a client asks for support, the team discovers there’s no retained calculation to show and has to reconstruct it under time pressure.
The third mistake is a certification claim that isn’t backed by the actual documents, writing “all suppliers hold FSC certification” without attaching certificate numbers or expiration dates. This gets questioned harder than not mentioning certification at all, because it reads like a deliberate vagueness rather than an oversight.
Should Carbon Footprint Data Go in the Report
Carbon footprint data usually belongs in Section 3 as a supporting metric, but the full calculation involves Scope 1, 2, and 3 emissions boundaries and conversion factor choices, details that go well beyond report structure on their own and deserve separate treatment. We’ll cover the calculation methodology in a follow-up piece.
At its core, an ESG procurement report for food containers is about presenting a multi-material procurement decision, not replicating a single-material swap success story. Filling out all four sections, policy definitions, supplier proof, quantified results, and a tracking mechanism, is what makes a report hold up under audit and client scrutiny, rather than reading as a sustainability statement written only for internal eyes.